Suez Canal Return: What Returning Container Ships Mean for Importers in 2027
Carriers are sending big ships back through Suez. Here is what that does to capacity, rates and the contracts you sign this winter.
In this report 9 sections
The Suez Canal return is real but partial. In August 2026, 1.68 million TEU of container capacity crossed the canal, up 184% from a year earlier, yet activity is still far below pre-crisis levels. Each ship that comes back frees capacity from the long detour around Africa, which pushes rates down over time.
Laneage covers freight, trade and supply chain operations for shippers and importers. This piece is for anyone who buys ocean freight and has to sign 2027 contracts before the picture is clear. It explains what is changing, why it is fragile, and what to write into your agreements.
What Is Actually Happening at Suez Right Now?
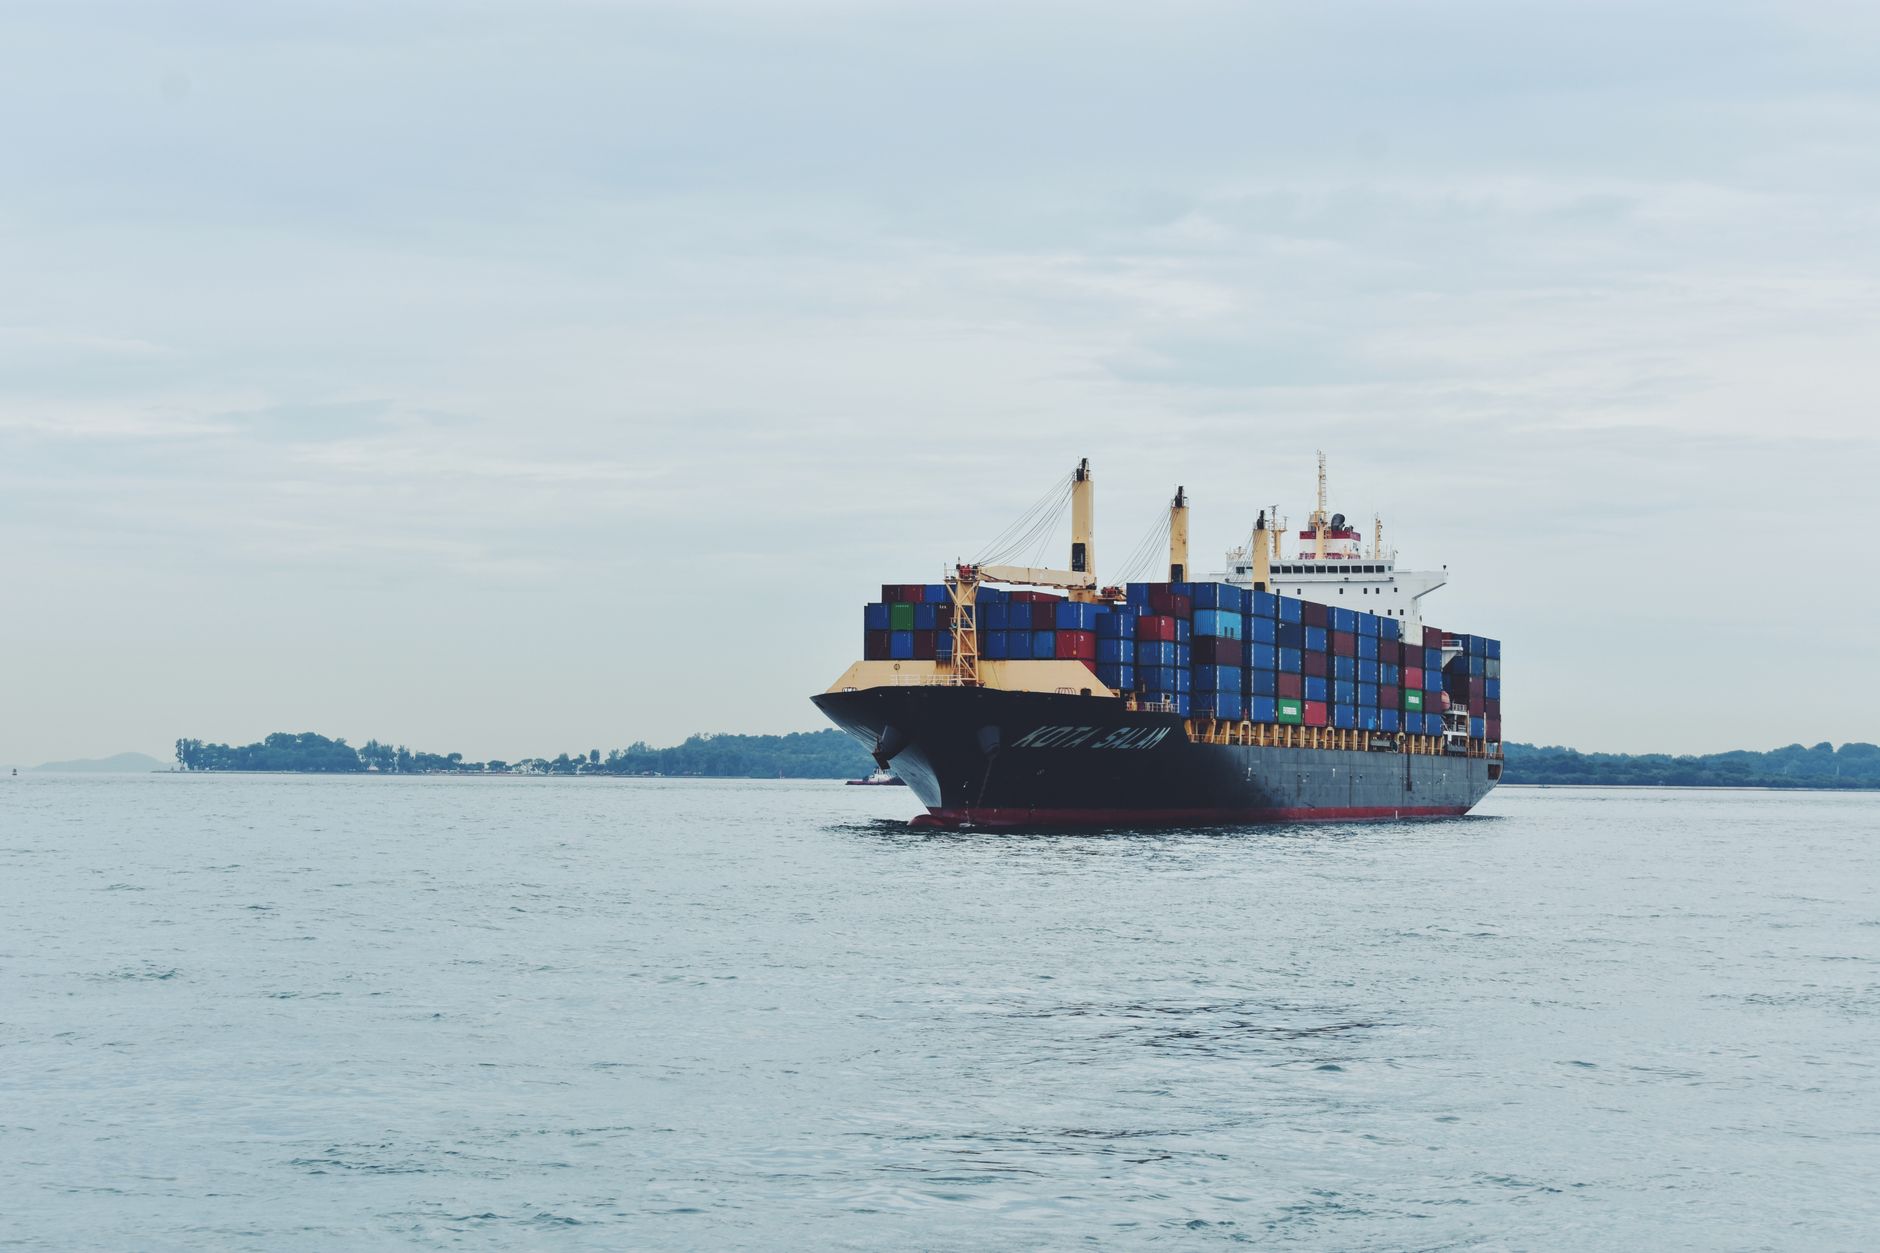
Carriers are moving ships back to the canal one service at a time. According to a September 5 analysis of August vessel movements, 196 ships transited the canal, up 36% from August 2025. Nine of them were larger than 20,000 TEU.
CMA CGM was the busiest carrier with 15 transits. Maersk made 11 and has moved more than 30% of its around-Africa volume back to the Suez route. MSC restored several East-West services on a case-by-case basis.
Not everyone is back. Hapag-Lloyd has stayed on the longer route even though it shares the Gemini Cooperation with Maersk. Cosco and Wan Hai are running northbound transits only. Sea-Intelligence puts the share of Asia-Europe westbound services using Suez at 19%.

Why Is the Return Still Fragile?
The return remains fragile because the route can close again with little warning. Carriers suspended transits in February 2026 after hostilities involving the United States and Iran. Every carrier planning a Suez routing knows the same thing could happen again.
The numbers show how far there is to go. Compared with August 2023, Suez ship transits are still about 65% lower and capacity is about 74% lower. January through August 2026 carried 7.2 million TEU, roughly 55% more than the same months of 2025, but over 1,186 vessels instead of 1,230. That means the ships are bigger, not more numerous. Average vessel size rose from about 3,800 TEU to about 6,000 TEU.
At Laneage, our editors read that as a signal about carrier behavior. Lines are testing the route with their largest, most efficient ships first. They are not yet committing whole networks.
How Does the Detour Eat Into Container Capacity?
Sailing around the Cape of Good Hope takes about 45 days on Asia-Europe routes, against about 30 days through Suez. Longer voyages mean each ship completes fewer round trips per year. The market effectively loses ships it technically still has.
The same analysis estimates the Cape diversion absorbs 5-7% of global vessel capacity, or 1.7 to 2.4 million TEU. At the end of August, 280 ships carrying 4.0 million TEU were on the Cape route. That is down from a peak of 380 ships and 5.5 million TEU.
A late 2025 industry report reached a similar figure. It said a full return would release more than 2 million TEU, about 9% of global capacity, into a market that already had excess supply.
What Does a Suez Return Do to Freight Rates?
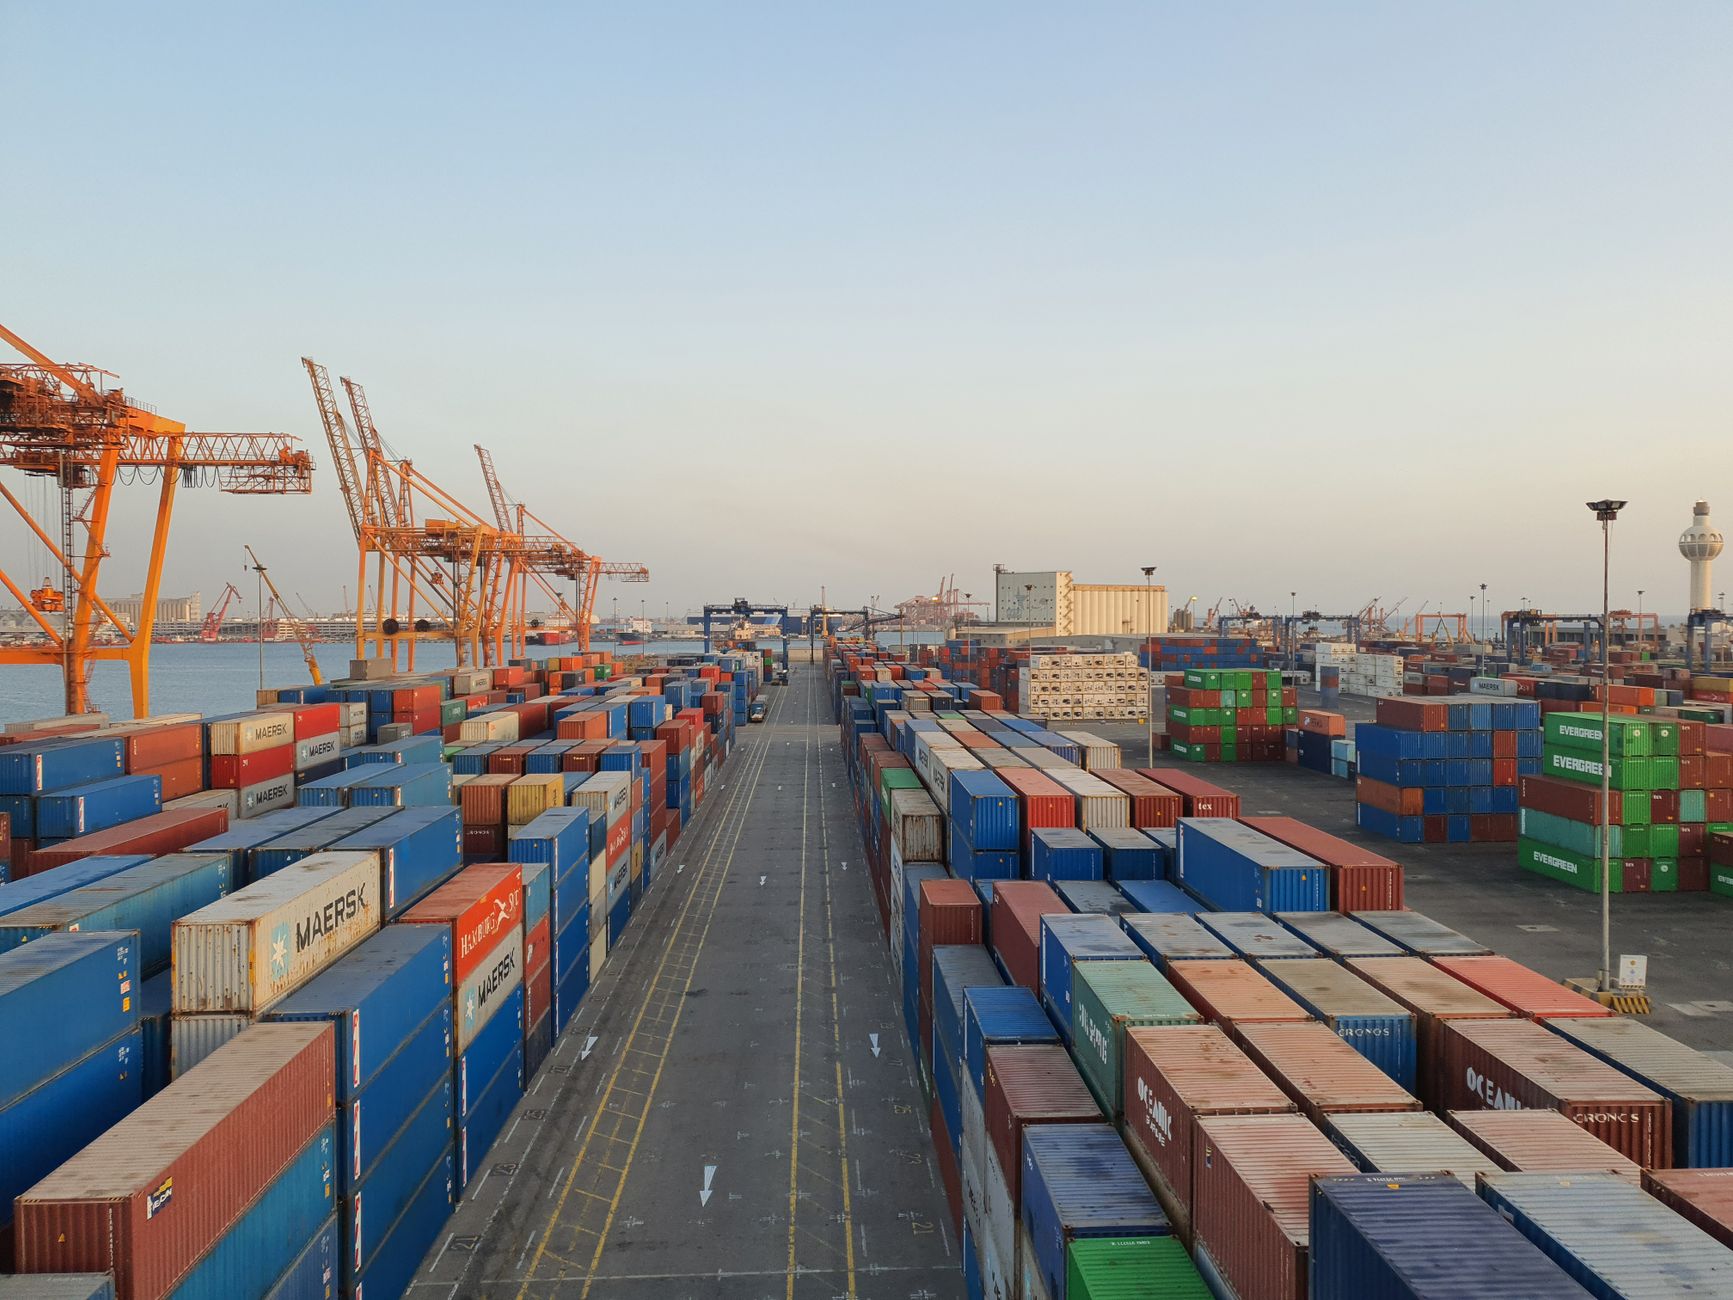
A Suez return should push container rates down over the medium term, but the first effect can run the other way. When many ships arrive early at European ports, terminals clog. Congestion absorbs capacity for weeks and can lift spot rates briefly.
Freightos analyst Judah Levine told the industry press that a short-term spike is likely as congestion grows. He expects rates to fall later as operations normalize. The same report noted that early-arriving vessels could reach European ports 7 to 10 days ahead of schedule, and that normalizing schedules could take about two months.
The longer-term math is harder on carriers. The Baltic and International Maritime Council (BIMCO) projected that ship demand could fall by up to 10% if Suez routings fully return. It expected fleet supply to grow 3% in 2026 and 3.5% in 2027, while demand grows 2.5% to 3.5% a year.
| Scenario | Capacity effect | Likely rate pressure |
|---|---|---|
| Partial return (today) | Modest relief, mostly on Asia-Europe | Soft, with local congestion spikes |
| Full return | Up to 9% of global capacity released | Strong downward pressure in 2027 |
| Route closes again | Capacity absorbed by the Cape detour | Rates rebound quickly |
Who Gains and Who Loses When Ships Return to Suez?
Shippers that move goods between Asia and Europe gain first. A voyage that takes 30 days instead of 45 cuts the time inventory sits on the water, which lowers carrying costs and shrinks the safety stock a buyer needs. For a company moving high-value goods, two weeks of working capital is a real number.
Carriers face the harder side of the trade. More effective supply with the same demand means less pricing power. The September analysis noted that a bank analyst expects this to weigh on carrier earnings, especially with new vessel deliveries arriving in 2027 and 2028.
Ports and truckers sit in the middle. Early-arriving ships bunch up at terminals, and drayage fleets feel it within days. In our experience covering freight, the first weeks after a routing change are the messiest, with missed appointments and storage charges that shippers did not budget for. Plan for a few weeks of friction when a service you rely on switches routes.
Smaller importers often learn about a routing change late, from a revised sailing schedule or a surcharge notice. Ask your forwarder to flag any service switch as soon as the carrier announces it. That gives you time to move a booking, adjust delivery appointments or warn customers about a changed arrival date.
Does This Matter If You Import Through U.S. Ports?
It matters indirectly. Suez is mainly an Asia-Europe route, so the first effects land in European trade lanes. U.S. importers feel the change when carriers redeploy ships and reprice capacity across trades.
BIMCO expected North American import volumes to rise about 2% in each of 2026 and 2027, which is modest growth into a market with more ships. Our analysis of transpacific rates and 2027 contracts covers the Pacific side of this. The practical point is that extra supply anywhere in the system gives buyers more leverage everywhere.
That leverage is only useful if you are in a position to use it. Importers locked into fixed multi-year rates at a high point will not benefit when spot rates drop. That is the main contracting risk for 2027.
How Should Importers Structure 2027 Ocean Contracts?
Keep your commitments short or index-linked, and build in review points. Do not sign a flat rate for twelve months based on today's spot market. The direction of rates depends on a canal that can close again.
The steps below are practical ways to build in flexibility.
- Ask for quarterly rate reviews tied to a published index.
- Split volume between a contract carrier and the spot market.
- Negotiate minimum quantity commitments you can realistically hit.
- Keep a second carrier qualified on every major lane.
- Add clauses covering rerouting, surcharges and transit time changes.
Our guide on how to negotiate freight rates walks through the leverage points in more detail. It applies directly here, because a softening market is when buyers can push for better terms.
What Should You Watch Between Now and Q1 2027?
Watch four signals: whether Hapag-Lloyd rejoins the route, how many large ships transit each week, whether European terminals report bunching, and any security incidents. Each one tells you whether the return is deepening or stalling.
Consider your supply-chain exposure as well. If a closure would strand inventory or lengthen lead times, a current supply chain risk map shows which products and suppliers are most exposed. Peak season is a bad time to find out.
Set a simple internal trigger for each signal. For example, if two or more large carriers reverse course, treat it as a closure and reopen rate talks. If weekly transits keep climbing for a full quarter, start asking carriers for lower rates at your next review. Written triggers keep the decision from turning into a debate during a busy shipping season.
Finally, remember that carriers also respond to oversupply. They can blank sailings, idle ships, scrap older vessels or slow-steam to protect rates. BIMCO noted about 750,000 TEU of recycling across 2026 and 2027 could ease part of the surplus. A rate collapse is possible, but it is not guaranteed.
Conclusion
The Suez return is a slow, uneven shift with a real downside risk if the route closes again. For importers, the right response is flexibility rather than a bet on direction. Keep contracts short, review often and qualify a second carrier on key lanes.
Next step: pull your current ocean agreements this week and check the term length, review dates and rerouting clauses. If any of them lock you in for a full year at a flat rate, raise it with your carrier before the market moves.